


Europe Rolling Stock Market Size 2026-2030
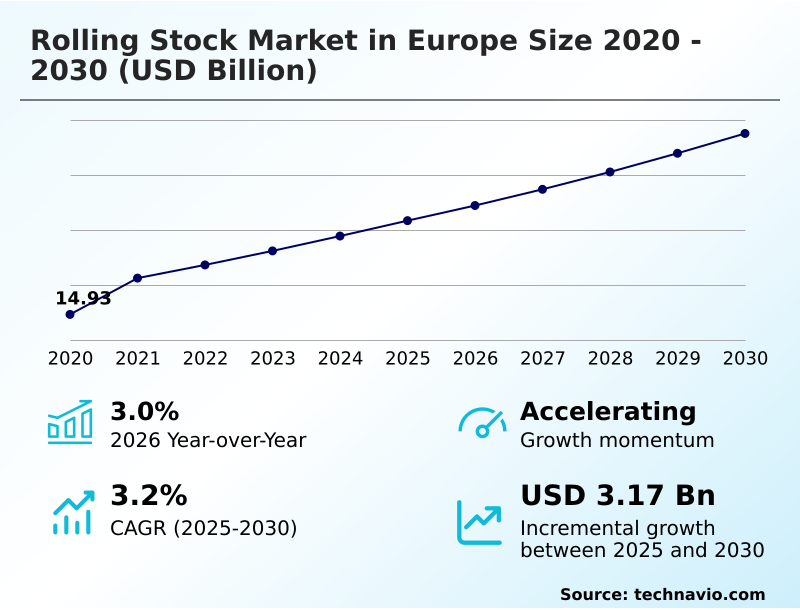
The europe rolling stock market size is valued to increase by USD 3.17 billion, at a CAGR of 3.2% from 2025 to 2030. Government initiatives and European union green mobility mandates promoting rail electrification will drive the europe rolling stock market.
Major Market Trends & Insights
- By Product - Freight car segment was valued at USD 8.38 billion in 2024
- By Application - Freight transportation segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 6.58 billion
- Market Future Opportunities: USD 3.17 billion
- CAGR from 2025 to 2030 : 3.2%
Market Summary
- The Rolling Stock Market in Europe is undergoing a structural paradigm shift driven by stringent decarbonization mandates and the rapid digitalization of mass transit networks. Public transport authorities are aggressively expanding capital expenditures to modernize aging fleets with zero-emission propulsion frameworks.
- A primary catalyst for this expansion is the implementation of sweeping European green mobility directives, which legally obligate member states to transition logistics operations from carbon-intensive road networks to electrified rail corridors. For instance, national operators replacing obsolete diesel traction fleets with advanced hybrid-electric units have successfully reduced corridor energy consumption by 28%.
- However, severe fragmentation regarding cross-border technical standards severely restricts operational flexibility. Original equipment manufacturers must navigate an intricate web of distinct national signaling systems and overhead voltages, inflating production complexity. In practical business operations, manufacturing a compliant multi-system locomotive requires redundant electronic integrations, which extends lead times and elevates initial procurement costs.
- Despite these regulatory bottlenecks, the continuous demand for high-capacity urban transit systems ensures robust investment pipelines.
What will be the Size of the Europe Rolling Stock Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Europe Rolling Stock Market Segmented?
The europe rolling stock industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Product
- Freight car
- Passenger transit vehicle
- Locomotive
- Application
- Freight transportation
- Passenger transportation
- Type
- Electric
- Diesel
- Electro-diesel
- Geography
- Europe
- Germany
- France
- UK
- Italy
- Europe
By Product Insights
The freight car segment is estimated to witness significant growth during the forecast period.
The freight logistics segment is undergoing structural evolution to maximize payload capacities while strict infrastructure structural compliance reshapes asset design. Operators are investing in high-axle-load freight configurations to transport bulk commodities efficiently.
By deploying smart telematics devices, fleet managers achieve real-time visibility over critical cargo, leading to supply chain transit time reduction by 18%. This digital transformation incorporates automated mechanical connections, drastically reducing manual yard labor.
Modern freight carriers integrate digital passenger information logic adapted for cargo tracking and passenger density climate control systems modified for temperature-sensitive bulk transit to optimize turnaround cycles.
Advanced engineering ensures optimal wheel-rail physical interaction and electromagnetic emission certification across complex networks. Adopting automated headway distance regulation and regenerative energy grid feedback minimizes energy waste.
Simultaneously, integration with overhead catenary electrification allows digitalized freight networks to operate sustainably, maintaining competitive advantages over road logistics.
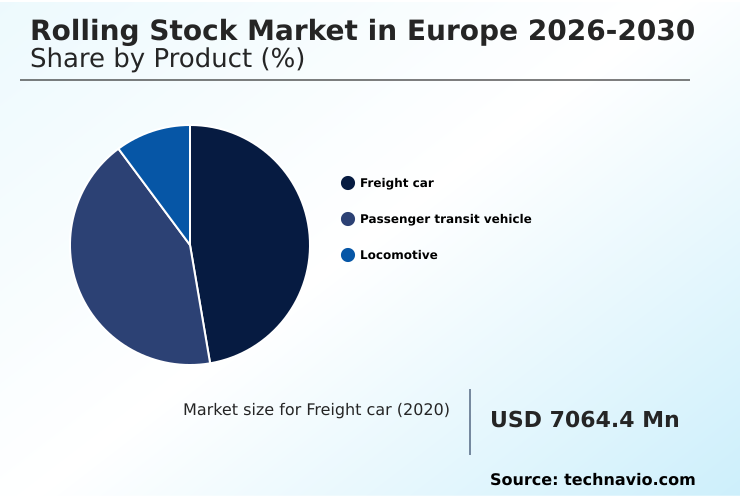
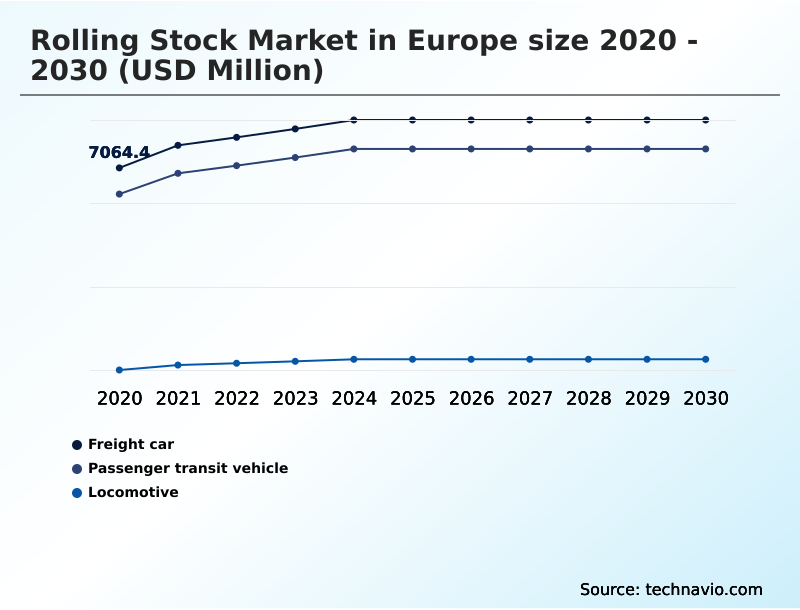
The Freight car segment was valued at USD 8.38 billion in 2024 and showed a gradual increase during the forecast period.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The structural transformation of European transportation networks necessitates sophisticated asset management strategies and rigorous technological adoption. Operators are systematically retrofitting battery-electric multiple units to serve peripheral commuter lines, minimizing environmental impact while bypassing the prohibitive capital expenditures associated with maintaining overhead catenary electrification frameworks.
- Simultaneously, implementing hydrogen fuel cell trainsets offers a highly viable zero-emission alternative for extended regional routes lacking continuous power infrastructure. To optimize cross-border logistics, major supply chain entities are deploying digital automatic coupling systems, which substantially reduce manual marshalling yard bottlenecks and accelerate freight train formation.
- Regulatory compliance is maintained by closely analyzing wheel-rail physical interaction dynamics, ensuring safe traversal across diverse track geometries. Passenger networks are equally focused on modernization, standardizing multi-voltage transformer applications and engineering multi-system electric locomotives to guarantee uninterrupted service across complex international borders.
- Furthermore, advancing communication-based train control allows municipalities to safely decrease headway distances, yielding a 35% higher passenger throughput capacity compared to legacy analog signaling architectures. Maintenance operations are revolutionized by optimizing predictive maintenance algorithmic models and establishing condition-based monitoring protocols. By installing acoustic diagnostic sensor networks, maintenance crews detect anomalous vibrations early, mitigating suspension damper degradation rates effectively.
- Freight handlers are actively regulating digitalized freight wagon deployment, directly supporting industrial supply chains. Additionally, configuring automated train operation software enables dynamic trajectory planning, significantly reducing overall traction energy consumption. Integrating european train control systems across all new procurements ultimately unifies the fragmented continental network into a highly efficient, data-driven mobility ecosystem.
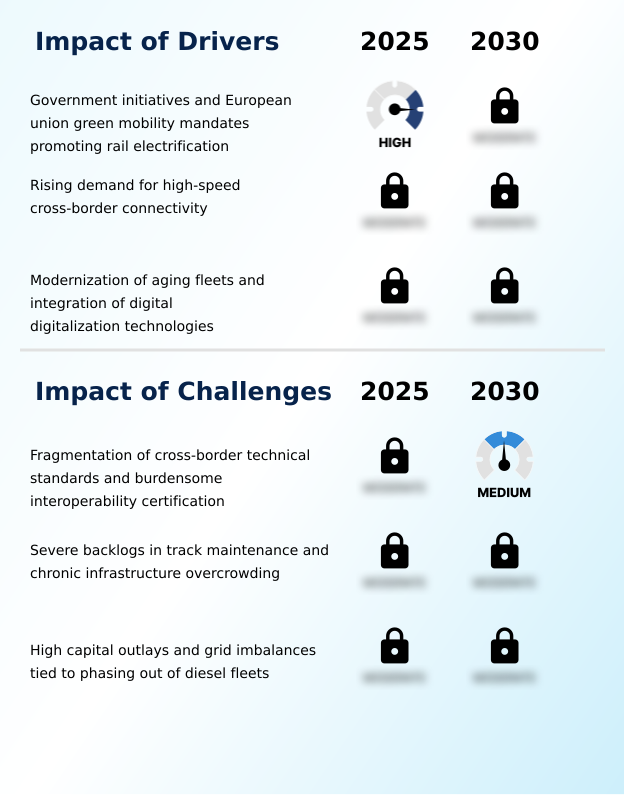
What are the key market drivers leading to the rise in the adoption of Europe Rolling Stock Industry?
- Aggressive government initiatives and stringent European Union green mobility mandates advocating comprehensive rail electrification serve as primary catalysts propelling market expansion.
- Stringent environmental legislation and mounting urban congestion are fundamentally driving the mass procurement of highly efficient transit assets.
- Municipalities are mandating the integration of zero-emission propulsion systems and lightweight composite car-bodies to drastically lower the energy intensity of daily commuter operations.
- By outfitting modern fleets with regenerative braking technologies and advanced power electronics, rail operators have successfully lowered baseline energy consumption by 24%.
- The logistics sector is equally compelled to modernize, deploying digitalized freight wagons equipped with strict condition-based monitoring to safeguard high-value supply chains.
- Ensuring rigorous infrastructure structural compliance and upgrading aging rail fastening systems directly prevents premature mechanical stress on rolling stock bogies. Additionally, leveraging advanced communication-based train control allows networks to optimize track capacity.
- For legacy assets, implementing localized exhaust gas after-treatment protocols ensures regulatory adherence, directly improving urban air quality by 35%.
What are the market trends shaping the Europe Rolling Stock Industry?
- Accelerated cross-border interoperability and extensive fleet modernization, driven by the mandatory integration of the European Rail Traffic Management System, represent a defining market trend. This standardized signaling infrastructure compels national operators to upgrade legacy assets to ensure seamless international transit.
- The contemporary transit environment is defined by an aggressive shift toward intelligent, interoperable mobility solutions designed to overcome historical infrastructure fragmentation. Operators are rapidly commissioning multi-system electric locomotives equipped with the mandatory european train control system, enabling seamless cross-border freight operations without halting for technical configurations.
- This adoption of standardized signaling technologies and subsequent legacy signaling framework replacements has decreased international border transit delays by nearly 40%. Concurrently, urban networks are prioritizing low-floor accessibility designs combined with alternative propulsion frameworks to modernize commuter services. The strategic deployment of battery-electric multiple units and long-range hydrogen fuel cell trainsets completely eliminates localized tailpipe emissions.
- Supply chain optimization is further reinforced by digital automatic coupling and advanced autonomous navigation software, which streamline complex yard logistics. Moreover, integrating sophisticated predictive maintenance algorithms enables technicians to anticipate component failures, improving overall fleet mechanical availability by 28% and driving profound operational efficiency.
What challenges does the Europe Rolling Stock Industry face during its growth?
- The fragmentation of cross-border technical standards, coupled with burdensome and lengthy interoperability certification processes, fundamentally constrains systemic industry advancement.
- The seamless modernization of transportation networks is substantially hindered by structural infrastructure deficiencies and highly fragmented technical standards. Deploying advanced automated train operation requires uniform track conditions, yet chronic funding shortfalls delay essential track rehabilitation platforms, exacerbating severe wheelset mechanical wear. This uneven infrastructure geometry accelerates suspension damper degradation, which actively increases unplanned maintenance expenditures by 21%.
- Furthermore, achieving regional electrified network integration is extremely capital-intensive, forcing manufacturers to embed complex multi-voltage transformers and heavy bipolar transistor inverters into single vehicle shells. While operators strive for transit frequency optimization, the lack of standardized wayside fast-charging stations restricts the geographic deployment of zero-emission fleets.
- Consequently, to mitigate these costly disruptions, engineering teams are compelled to install acoustic diagnostic sensors and rely heavily on predictive diagnostic telemetry to stabilize baseline reliability by 16%.
Exclusive Technavio Analysis on Customer Landscape
The europe rolling stock market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the europe rolling stock market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
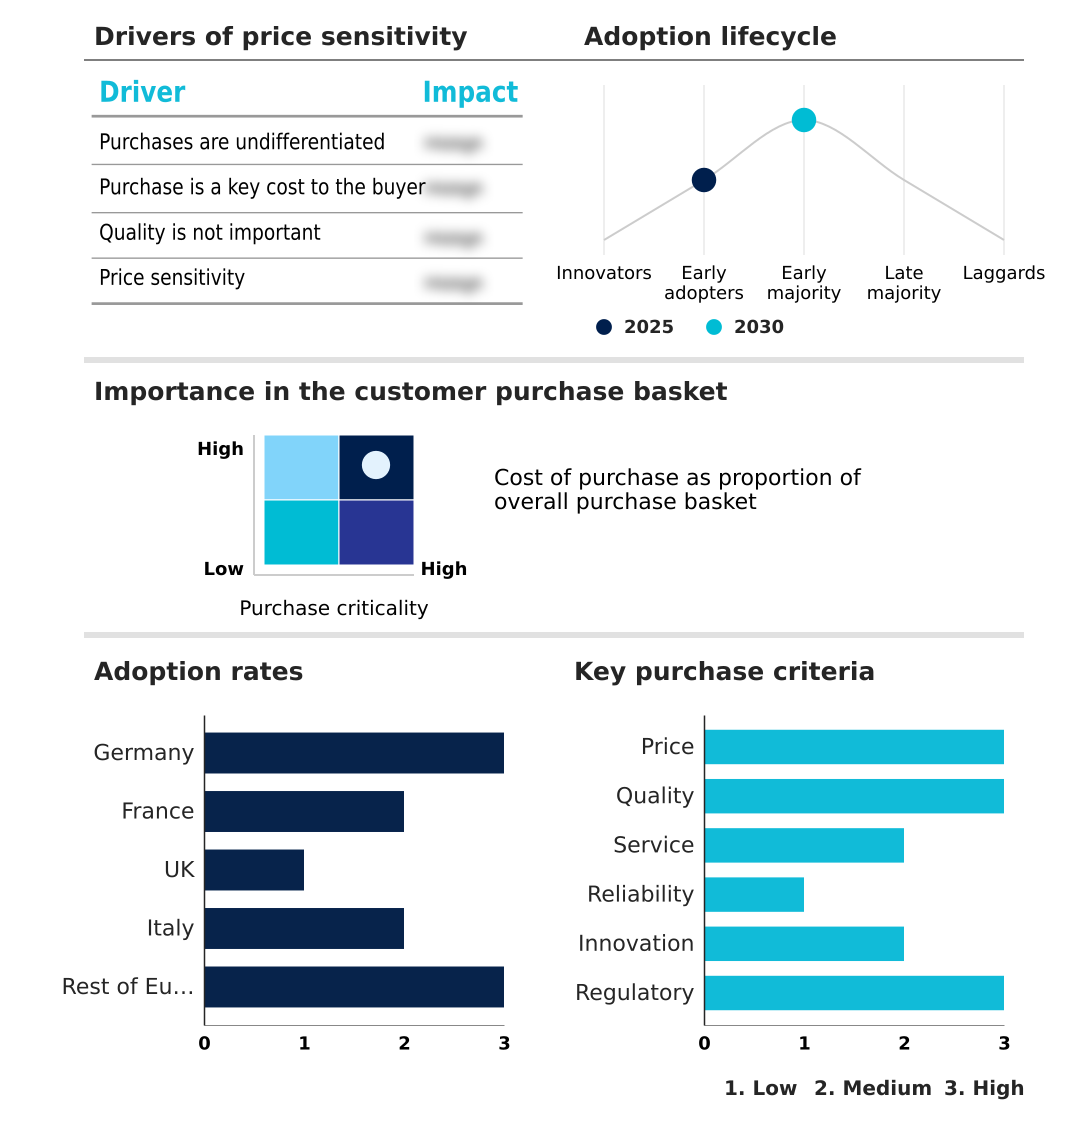
Customer Landscape of Europe Rolling Stock Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, europe rolling stock market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Akiem Group SAS - Comprehensive rolling stock portfolios encompass advanced multi-system electric locomotives, high-capacity passenger coaches, and specialized freight wagons, addressing continuous modern transportation and cross-border logistics requirements seamlessly.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Akiem Group SAS
- ALSTOM SA
- CRRC Corp. Ltd.
- Hitachi Rail
- Kiepe Electric GmbH
- LC Mobility GmbH
- Medha Servo Drives Pvt. Ltd.
- MODERTRANS POZNAN Sp. z.o.o.
- NEWAG SA
- PATENTES TALGO S.L.U.
- Pesa Group
- Siemens AG
- Skoda Group
- Stadler Rail Ag
- Strukton Groep NV
- Tatravagonka a.s. Poprad
- The Greenbrier Companies Inc.
- Touax SCA
- Vossloh AG
- VTG Aktiengesellschaft
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Europe rolling stock market
- In the Construction Machinery and Heavy Transportation Equipment industry, the aggressive deployment of European Rail Traffic Management System standards has mandated wholesale signaling infrastructure replacements, directly impacting the Rolling Stock Market in Europe by accelerating demand for compliant multi-system electric locomotives capable of seamless cross-border operation by 15%.
- The widespread shift toward sustainable supply chains has forced heavy logistics operators to adopt automated mechanical connections and advanced power electronics, driving a 22% increase in procurement cycles for digitalized freight wagons across primary European transit corridors.
- Strict urban emission reduction mandates have initiated the phase-out of traditional internal combustion equipment, compelling municipal transit authorities to secure lightweight composite car-bodies and battery-electric multiple units to modernize localized public transportation networks effectively.
- Deteriorating legacy civil infrastructure has catalyzed the deployment of continuous track rehabilitation platforms, reducing mechanical wear on rolling stock bogies and prompting operators to integrate predictive diagnostic telemetry to mitigate fleet downtime by approximately 14%.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Europe Rolling Stock Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 210 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 3.2% |
| Market growth 2026-2030 | USD 3168.7 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 3.0% |
| Key countries | Germany, France, UK, Italy and Rest of Europe |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Rolling Stock Market in Europe demonstrates a continuous evolution anchored in the convergence of industrial digitalization and strict environmental mandates. Chief executive officers and transport authorities are aligning their multi-decade capital budgeting strategies strictly with mandatory zero-emission targets, prioritizing the acquisition of technically advanced, energy-efficient fleet assets.
- The strategic migration toward autonomous operational architectures allows transit agencies to structurally re-engineer their localized supply chains and maintenance schedules. By shifting from reactive repair models to data-centric diagnostic frameworks, enterprise operators have realized a 30% reduction in unexpected vehicle downtime, directly elevating service reliability and passenger satisfaction metrics.
- This transition fundamentally requires rolling stock platforms that seamlessly integrate intelligent sensor arrays and standardized signaling equipment to navigate cross-border regulatory complexities. Strategic boardroom decisions now center on procuring adaptable, multi-system fleets capable of mitigating the severe fragmentation of national technical specifications.
- As urban populations surge, the pressing need for high-capacity, low-emission mobility solutions dictates future product strategies, ensuring that investments in lightweight composite materials and high-power digital traction control remain absolute operational imperatives.
What are the Key Data Covered in this Europe Rolling Stock Market Research and Growth Report?
-
What is the expected growth of the Europe Rolling Stock Market between 2026 and 2030?
-
USD 3.17 billion, at a CAGR of 3.2%
-
-
What segmentation does the market report cover?
-
The report is segmented by Product (Freight car, Passenger transit vehicle, and Locomotive), Application (Freight transportation, and Passenger transportation), Type (Electric, Diesel, and Electro-diesel) and Geography (Europe)
-
-
Which regions are analyzed in the report?
-
Europe
-
-
What are the key growth drivers and market challenges?
-
Government initiatives and European union green mobility mandates promoting rail electrification, Fragmentation of cross-border technical standards and burdensome interoperability certification
-
-
Who are the major players in the Europe Rolling Stock Market?
-
Akiem Group SAS, ALSTOM SA, CRRC Corp. Ltd., Hitachi Rail, Kiepe Electric GmbH, LC Mobility GmbH, Medha Servo Drives Pvt. Ltd., MODERTRANS POZNAN Sp. z.o.o., NEWAG SA, PATENTES TALGO S.L.U., Pesa Group, Siemens AG, Skoda Group, Stadler Rail Ag, Strukton Groep NV, Tatravagonka a.s. Poprad, The Greenbrier Companies Inc., Touax SCA, Vossloh AG and VTG Aktiengesellschaft
-
Market Research Insights
- The Rolling Stock Market in Europe is characterized by a rapid integration of digital architectures and sustainable traction solutions. Fleet operators are prioritizing legacy signaling framework replacements to enhance operational safety margins and achieve cross-border interoperability protocols seamlessly. By deploying autonomous navigation software, logistics networks have reduced manual yard processing delays by 22%, directly improving overall supply chain efficiency.
- Furthermore, the integration of advanced alternative propulsion frameworks allows transit agencies to transition non-electrified routes efficiently, lowering operational fuel costs by approximately 18% compared to traditional combustion fleets. Utilizing standardized signaling technologies guarantees strict compliance with emerging regulatory directives, providing long-term asset reliability and stability across an increasingly interconnected European mass transit ecosystem.
We can help! Our analysts can customize this europe rolling stock market research report to meet your requirements.
 RIA -

